Home Buying · Bell County, Texas
Foreclosures in KilleenA 2026 Buyer’s Playbook
Foreclosures in Killeen come in three completely different markets hiding behind one word. Knowing which one you are buying in — pre-foreclosure, courthouse auction, or bank-owned — decides whether you get a discount or a disaster.
1st TueBell County Sale Day
21 DaysMinimum Sale Notice
NoneRedemption After Sale
$0 DownVendee Financing
Quick Answer
How do you buy foreclosures in Killeen, Texas?
There are three stages, and each is a different transaction. Pre-foreclosure means buying from the owner before the sale, often as a short sale. The trustee auction is held on the first Tuesday of each month, between 10 a.m. and 4 p.m., at the Bell County Clerk's alcove outside the Justice Complex at 1201 Huey Drive in Belton — cash or cashier's check, no inspection, no financing. REO means the lender or agency already owns it and sells it like a normal listing, with financing allowed.
For most buyers, REO is the realistic path. VA-acquired homes near Fort Hood are sold through VRM Properties, which currently lists roughly 20 properties in Killeen priced from about $124,950 to $279,000 — and offers Vendee financing with little to no money down and no mortgage insurance, open to veterans and non-veterans alike.
On this page
- Current foreclosure listings
- The three stages of a foreclosure
- The Bell County trustee sale, first Tuesday
- What you actually get at auction
- VA foreclosures and Vendee financing
- HUD, Fannie, Freddie and bank REO
- No seller’s disclosure: protect yourself
- Are foreclosures actually cheaper?
- If you are facing foreclosure yourself
- Key terms defined
- Frequently asked questions
A foreclosure is not a type of house. It is a stage in a legal process — and the stage you buy at determines your price, your risk, and whether you are allowed to look inside first.
Most people searching for foreclosures in Killeen picture a courthouse auction with bargain prices. That market exists, it runs on the first Tuesday of every month in Belton, and it is almost entirely the province of cash investors who accept real risk. The market that actually serves an ordinary buyer — including a soldier at Fort Hood using a VA loan — is the bank-owned and agency-owned inventory that comes to market after the auction, with clear title and normal financing.
This guide separates the three stages of foreclosures in Killeen, walks the Bell County process by the actual statute and the actual sale location, explains the VA-acquired inventory sold through VRM Properties, and closes with what to do if you are the one behind on payments rather than the one shopping.
Current Foreclosure Listings in Killeen
These are live MLS listings updated throughout the day. Bank-owned and pre-foreclosure properties move quickly, so what appears here this morning may be under contract by evening.
Live Foreclosure Listings — Killeen & Central Texas
Bank-owned, REO and distressed properties currently on the market across the Fort Hood corridor. Save a search and get new listings the day they hit.





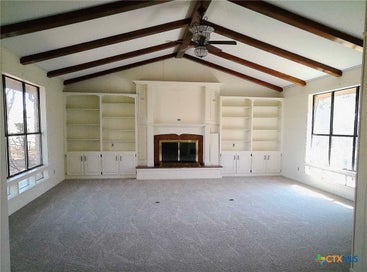


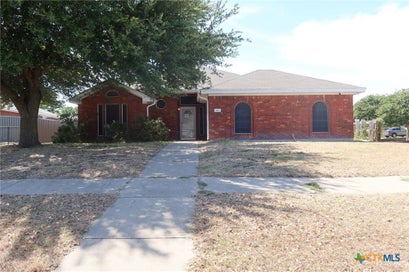


Not seeing what you want? Many foreclosures in Killeen never reach the MLS — tell us what you are looking for and we will watch the courthouse list and the agency channels for you.
The Three Stages of Foreclosures in Killeen
Pre-foreclosure, trustee auction, and REO. Each has a different seller, a different level of risk, and a different answer to the question of whether you can finance the purchase or inspect the house.
| Pre-Foreclosure | Trustee Auction | REO / Bank-Owned | |
|---|---|---|---|
| Who sells | The homeowner, with lender approval | A substitute trustee | The lender or federal agency |
| Can you inspect? | Yes | No — sold sight unseen | Yes |
| Financing allowed | Yes, including VA | No — cash or cashier’s check | Yes, including VA |
| Title risk | Normal, with title policy | High — senior liens can survive | Low — usually cleared |
| Occupancy risk | Low | You may have to evict | Usually vacant |
| Typical discount | Modest | Largest, if you are right | Modest to moderate |
| Right for | Patient buyers, investors | Experienced cash investors | Most buyers, including VA |
Read that table honestly before you go hunting for foreclosures in Killeen. The advertised bargains on foreclosure listing sites are usually auction properties, and the auction is the one stage where you cannot see the inside, cannot get a loan, and cannot back out. The REO column is where financed buyers actually close.
Where Foreclosures in Killeen Are Auctioned: First Tuesday in Belton
Texas foreclosure sales happen on the first Tuesday of the month between 10 a.m. and 4 p.m. In Bell County the designated location is the County Clerk's alcove east of the main entrance of the Bell County Justice Complex, 1201 Huey Drive, Belton.
Texas is a non-judicial foreclosure state, which means foreclosures in Killeen involve no courtroom and no judge. Under Property Code Section 51.002 the process moves faster than buyers from other states expect, and that speed is the reason so much distressed inventory reaches the courthouse steps rather than the MLS.
- Notice of default and 20 days to cureBefore any of the foreclosures in Killeen reach a sale date, the mortgage servicer sends the borrower written notice by certified mail and must allow at least 20 days to cure the default before a sale notice may be issued.
- Notice of sale, at least 21 days outThe sale notice must be given at least 21 days before the sale date. It is posted at the courthouse door, filed with the county clerk, and mailed to the debtor. Bell County publishes filed notices, and the clerk keeps them in a public file.
- The first TuesdaySales are held on the first Tuesday of the month between 10 a.m. and 4 p.m. If that Tuesday falls on January 1 or July 4, the sale moves to the first Wednesday. Bidding must begin at the time stated in the notice or within three hours after it.
- The biddingThe lender opens with a credit bid up to what it is owed. If nobody outbids it, the lender takes the property back and it becomes REO. Most foreclosures in Killeen end right here.
- Payment on the spotThe winning bidder pays immediately or within whatever short window the trustee allows — cash or cashier's check. Fail to pay and the bidding reopens.
- You get a trustee’s deedForeclosures in Killeen bought at auction convey by trustee’s deed, not a warranty deed, and no title policy from the trustee. Whatever you bought, you now own.
Verify each month's list of foreclosures in Killeen and the current location directly with the Bell County Clerk's foreclosure notice page before you show up. Sale locations are set by the commissioners court and lists change until the morning of the sale — postponements are routine.
What You Actually Get Buying Foreclosures in Killeen at Auction
A trustee's deed conveys exactly the interest the borrower held — no more, no less. Senior liens survive, property taxes survive, and after a standard mortgage foreclosure in Texas the former owner has no right of redemption.
The Five Risks Nobody Advertises
- With foreclosures in Killeen you are bidding on a lien position, not a house. If you buy at a second-lien sale, the first mortgage survives and is now your problem. Title research before the sale is not optional.
- You cannot go inside. No inspection, no appraisal, no walk-through. Interior condition is a guess, and distressed properties are frequently stripped.
- The house may be occupied. Removing occupants means filing a forcible detainer action in justice court, which takes time and money.
- Unpaid property taxes follow the property. In a county with a 1.46 percent median effective rate, several years of arrears is real money.
- No financing, no contingencies, no option period. The Texas option period that protects ordinary buyers does not exist at a trustee sale.
Foreclosures in Killeen do come with one genuine consolation. Because Texas grants no redemption right after a regular deed-of-trust foreclosure, a winning bidder owns the property outright the same day. That is different from a tax sale, where a former owner can redeem within 180 days on non-homestead property, or up to two years on a homestead or agricultural property, by paying a redemption premium of 25 to 50 percent.
VA Foreclosures in Killeen and Vendee Financing
When the VA acquires a home after a foreclosure, it is sold through VRM Properties — and it can be bought by anyone, veteran or not. Vendee financing offers little to no money down with no mortgage insurance, and it does not use your VA entitlement.
This is the most under-used opportunity among foreclosures in Killeen, and the reason is simple: almost nobody knows the inventory exists. VA-acquired properties are not listed the way ordinary homes are. They sit on the VRM Properties listing site, which currently shows roughly 20 homes in Killeen and Bell County priced from about $124,950 to $279,000, mostly three- and four-bedroom houses.
Who Can Buy
Anyone. Veterans, non-veterans, owner-occupants and investors are all eligible for Vendee financing on VA-acquired properties. You do not need a VA loan, a Certificate of Eligibility, or military service.
That surprises people, and it is why a civilian investor and a soldier can end up bidding on the same house.
Why Vendee Is Different
Little to no money down, no mortgage insurance requirement, competitive rates, no prepayment penalty, and origination and funding fees that qualified borrowers may roll into the loan. The seller may also contribute toward closing costs.
Critically, it does not consume your VA entitlement — so a veteran can use Vendee here and keep entitlement available for the next duty station.
VRM offers three ways to buy foreclosures in Killeen: in-person auction, online auction, and a traditional written offer. For a soldier at Fort Hood, the traditional offer path behaves much like any other purchase — which means your agent, your inspection and your timeline all work normally.
Like all foreclosures in Killeen, a VA-acquired home is sold as-is. If you are financing with a standard VA loan rather than Vendee, the property must still satisfy VA minimum property requirements, so read our guide to the VA appraisal in Killeen before you write an offer on a property with an aging roof or a dead HVAC.
Where to Find Foreclosures in Killeen: HUD, Fannie, Freddie and Bank REO
Federal agencies and lenders each sell their foreclosed inventory through separate channels. Watching only one of them means missing most of the foreclosures in Killeen that a financed buyer can actually purchase.
| Source | What It Sells | Notable For Buyers |
|---|---|---|
| VRM Properties | VA-acquired homes, plus some servicer inventory | Vendee financing; open to veterans and non-veterans |
| HUD HomeStore | FHA-insured foreclosures | Owner-occupant bidding priority window before investors |
| Fannie Mae HomePath | Fannie Mae REO | First-look period for owner-occupants |
| Freddie Mac HomeSteps | Freddie Mac REO | Similar owner-occupant priority |
| Bank and servicer REO | Conventional lender inventory | Usually listed on the MLS like any other home |
| Bell County Clerk | Trustee sale notices, not listings | The monthly auction list, filed 21+ days ahead |
The owner-occupant priority windows on foreclosures in Killeen are worth knowing. Several agency programs give buyers who will live in the home an exclusive bidding period before investors may bid. For a military family relocating to Fort Hood, that is a genuine advantage over the cash investors who dominate the auction.
“At the courthouse you are buying a lien and a rumor. In an REO you are buying a house you have walked through. The difference is worth more than the discount.” Homevets Realty · Killeen, Texas
No Seller’s Disclosure on Foreclosures in Killeen: How to Protect Yourself
Foreclosure and lender sales are exempt from the Texas Seller's Disclosure Notice under Property Code 5.008. The seller does not have to tell you what is wrong with the house, because the seller genuinely does not know.
That exemption is the defining practical feature of foreclosures in Killeen of buying foreclosures in Killeen through the REO channel. A bank that has never set foot in the property cannot describe its history, its leaks, or its foundation. What replaces the disclosure is your own diligence, and there are five things you should never skip:
- Negotiate an option period on any of the foreclosures in Killeen you pursue, and use every day of it. Even on an as-is sale, the option period buys you the right to inspect and to walk. Read our Texas option period guide for the mechanics.
- Get a full inspection plus specialists. A structural engineer if there is cracking, a plumber's hydrostatic test on an older slab, an HVAC technician on anything past fifteen years.
- Buy a title policy and read the commitment. Exceptions and outstanding liens are disclosed there, and this is the document that protects you.
- Check the tax account for arrears. Confirm what is owed and whether the assessed value is realistic — a distressed property is often over-assessed, which is grounds for a Bell County property tax protest.
- Price the repairs before you price the offer. Written contractor bids, not estimates. Roof, HVAC, plumbing and foundation are the four that turn a bargain into a loss.
One legal note worth carrying on foreclosures in Killeen: the disclosure exemption does not license concealment. Every exemption still carries liability for intentional fraud, so a lender or trustee who actively hides a known defect remains exposed.
Are Foreclosures in Killeen Actually Cheaper?
Sometimes, and less often than advertised. In a market where the average Killeen home value is about $220,448 and roughly half of all sales close below list price, an ordinary well-negotiated purchase can land close to REO pricing without the condition risk.
Run the arithmetic on foreclosures in Killeen before the romance. A foreclosure listed $25,000 under comparable sales that needs a $12,000 roof, an $8,000 HVAC system and $6,000 of flooring and paint is not a discount — it is a job you are being paid $1,000 to take on, assuming nothing else is wrong. And something else is usually wrong, because the previous owner stopped maintaining the property long before they stopped paying for it.
Where foreclosures in Killeen genuinely win: buyers who can do their own work, investors buying for the long hold, and anyone who finds a structurally sound house whose problems are cosmetic. Where they lose: a family on a PCS timeline who needs to move in within 45 days and cannot absorb a surprise.
The Fort Hood Timing Factor
REO transactions frequently run longer than standard sales because corporate sellers use their own addenda and approval chains. If you are on PCS orders with a report date, factor that in before you write the offer — and see our guide to buying near Fort Hood for how to sequence a move.
If You Are Facing Foreclosure on Your Own Killeen Home
You have options, and they all get better the earlier you act. Once a sale notice is filed, you generally have at least 21 days — and selling before the sale usually preserves far more equity than letting the auction happen.
If you are reading about foreclosures in Killeen because you are behind rather than shopping, start here. Contact your servicer and ask about reinstatement, a repayment plan, forbearance, or a loan modification. VA borrowers should also contact a VA loan technician, who can intervene with the servicer on your behalf regardless of who wrote the loan. And talk to a HUD-approved housing counselor — the counseling is free, and they work for you rather than for the lender.
If keeping the home is not realistic, selling ahead of the foreclosures in Killeen calendar is almost always the better outcome. Killeen homes go pending in a median of about 37 days, which means a sale started early can beat a posted sale date. A completed sale protects the equity you have and keeps a foreclosure off your credit, and if you owe more than the home is worth, a short sale negotiated with the lender is still a materially better result than a foreclosure on your record.
The first step is knowing your number. Get a current valuation before you make any decision — you may have more equity than you think, and equity changes every option on the table.
Key Terms, Defined
- Non-judicial foreclosure
- The Texas process behind foreclosures in Killeen, under Property Code Chapter 51, in which a lender forecloses through a trustee sale without going to court.
- Trustee’s deed
- The instrument conveying property at a foreclosure auction. It transfers only the interest the borrower held, with no warranties beyond title.
- REO
- Real estate owned — a property the lender or agency took back at the sale and now markets like a normal listing. Most foreclosures in Killeen that a financed buyer can purchase are REO.
- Pre-foreclosure
- The stage of foreclosures in Killeen after default but before the trustee sale, when the owner may still sell, often as a short sale with lender approval.
- Short sale
- A sale for less than the mortgage balance, requiring lender consent. Slower than a normal sale, but far better for the seller's credit than a foreclosure.
- Credit bid
- The lender's opening bid at auction, up to the amount it is owed, made without cash changing hands.
- Vendee financing
- The financing program available on VA-acquired properties. Open to veterans and non-veterans, with little to no down payment, no mortgage insurance, and no use of VA entitlement.
- Right of redemption
- The right to reclaim property after a sale. It does not exist after a regular Texas mortgage foreclosure, but does after a tax sale — 180 days, or two years on a homestead.
Frequently Asked Questions About Foreclosures in Killeen
On the first Tuesday of each month between 10 a.m. and 4 p.m., at the Bell County Clerk's alcove east of the main entrance of the Bell County Justice Complex, 1201 Huey Drive, Belton. If the first Tuesday is January 1 or July 4, the sale moves to the first Wednesday. Notices are filed with the county clerk at least 21 days before the sale, and lists change up to the morning of the sale.
Yes, on an REO or pre-foreclosure purchase, but not at the trustee auction, which requires cash or a cashier's check the same day. A VA loan on foreclosures in Killeen still requires the property to meet VA minimum property requirements, so a home with an active roof leak or no working heat will need repairs before closing. Vendee financing on VA-acquired homes is a separate program and does not use your entitlement.
No. VA-acquired properties sold through VRM Properties are open to anyone, and Vendee financing is available to veterans, non-veterans, owner-occupants and investors. There is no Certificate of Eligibility requirement and no service requirement. This is one of the few genuinely open doors among foreclosures in Killeen.
On an REO or pre-foreclosure purchase, yes — negotiate an option period and inspect exactly as you would on any other home. At a trustee auction, no. Auction properties are sold sight unseen with no interior access, no appraisal and no contingencies, which is the single biggest reason ordinary buyers should stay out of the courthouse market.
Not after a standard Texas mortgage foreclosure. There is no right of redemption, and the winning bidder owns the property immediately. Tax sales are different: a former owner may redeem within 180 days on non-homestead property, or up to two years on a homestead or agricultural property, by paying a redemption premium of 25 to 50 percent plus recoverable costs.
Sometimes. With the average Killeen home value near $220,448, values off about 1.1 percent over the past year, and a large share of ordinary sales closing below list price, the gap between a negotiated conventional purchase and an REO is narrower than most buyers assume. Price the repairs with written bids before you decide the discount is real.
Contact your servicer immediately and ask about reinstatement, a repayment plan, forbearance or a modification. VA borrowers can also request help from a VA loan technician. Speak with a HUD-approved housing counselor, which is free. Then get a current valuation, because selling before the trustee sale usually preserves more equity and protects your credit far better than letting the foreclosure complete.
Sources and disclaimer: Foreclosure sale timing, notice periods and the designated sale location come from Texas Property Code Chapter 51 and the Bell County Clerk's published foreclosure information. VA-acquired property counts, price ranges and Vendee financing terms are from VRM Properties and were current when this article was published; inventory changes constantly. Home value figures are Zillow market data as of July 2026. Homevets Realty is a licensed Texas real estate brokerage, not a lender, law firm or housing counseling agency. This article is general information, not legal, tax or financial advice. Confirm every sale date, notice and property condition independently, and consult a Texas attorney before bidding at a trustee sale.
Shopping Foreclosures — or Trying to Avoid One?
Homevets Realty is veteran-owned and has closed more than 5,000 transactions across the Fort Hood corridor. We will show you which foreclosures in Killeen are worth the risk, and if you are the one behind on payments, we will tell you straight what your options are.
More: What’s my home worth · Killeen rental market · Seller guide · Fort Hood relocation · Homes for Heroes · Killeen insights